

Upgrade - Boost Money
4.1

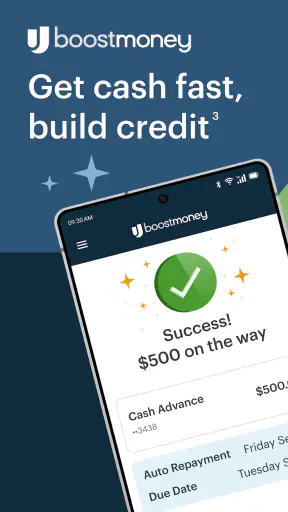
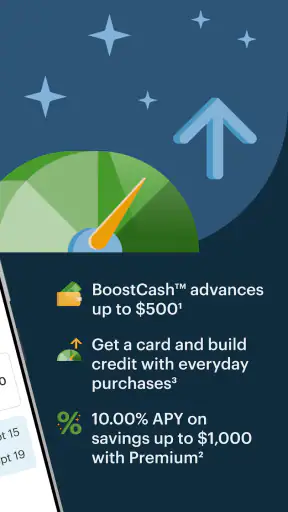
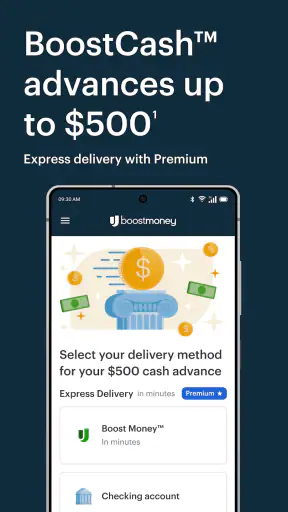
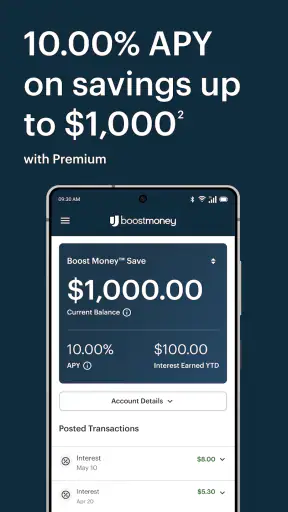
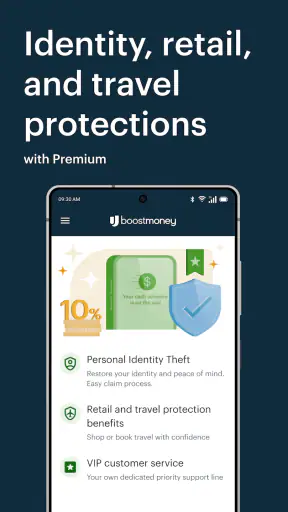
I approached Upgrade - Boost Money as a finance app for people who want spending, saving, and credit-building tools in one place rather than several disconnected services. My first impression was that its appeal depends less on flashy extras and more on how comfortably it fits into ordinary money routines: checking what is available, watching spending, setting money aside, and staying aware of credit progress. That combination makes it interesting for someone who wants a single financial companion, but it also means the app deserves a closer look than its short store description suggests.
Developed by Upgrade, Inc., this free app sits in the finance category and is rated for Everyone. It has reached over 50 thousand installs, with a 4.1 average from 172 ratings and 51 written reviews. Those figures suggest a real but still fairly modest user base, so I would treat it as a focused option rather than a universally established replacement for every banking or credit service. The release date is February 27, 2026, and the current version is 1.3.0, which places it in an early stage where a clean experience matters, but long-term refinement will also be important.
How quickly the money experience feels in everyday use
With a finance app like this, “speed” is not only about how fast a screen opens. I care about how quickly I can understand my position and decide what to do next. The strongest concept behind Upgrade - Boost Money is the reduced mental switching between spending, saving, and credit-related tasks. Instead of opening one app to review spending and another to think about credit, I can approach those jobs from one financial workspace.
That unified approach can make a difference during small, time-sensitive moments. Imagine standing in a shop and wondering whether a purchase will interfere with a bill later in the week. A useful finance app should help me answer that question without turning the process into a long budgeting session. Upgrade - Boost Money is best suited to that kind of quick check: open it, review the relevant money picture, and make a more deliberate choice.
I would not judge it by the speed of a single tap alone. Financial information can involve loading, verification, or updates that are naturally more deliberate than opening a calculator. A responsible user should also avoid treating a displayed balance as permission to spend every available amount. The app can support awareness, but it cannot replace a complete view of pending obligations, external accounts, or personal priorities.
One practical habit I found useful is separating “available for today” from “safe for the month.” Even if the interface makes current money easy to see, I would still keep a short note of upcoming rent, subscriptions, transport, and irregular expenses. This is a non-obvious trade-off: a consolidated app can reduce friction, but convenience may encourage overconfidence if I stop thinking beyond the current screen.
What happens when several financial tasks overlap
The heavier moments are not necessarily moments when the app is technically busy. They are the points when I ask it to support several decisions at once. For example, after receiving income, I might want to cover regular expenses, move a portion toward savings, and check whether my spending pattern is helping or hurting my credit goals. That is where the promise of combining these areas becomes meaningful.
In a realistic weekly routine, I could open the app after grocery shopping, review the effect of that purchase, and then decide whether the remaining discretionary amount is still comfortable. Later, I could use the same financial context while thinking about a larger payment. This workflow is more useful than checking isolated transactions because it connects the immediate purchase with broader money behavior.
There is also a risk of cognitive overload. Spending, saving, and credit are related, but they are not interchangeable. Saving is about building a reserve; spending is about managing cash flow; credit is about longer-term financial history and responsible borrowing behavior. I would not assume that improvement in one automatically fixes the others. The app is most helpful when I use each area for its own purpose instead of expecting a single score or dashboard to summarize my whole financial health.
For heavy use, I would recommend a short routine rather than constant checking. A morning glance can confirm the day’s position, while a weekly review can handle categories and upcoming commitments. Checking repeatedly after every purchase may create anxiety without improving decisions. This is one of the app’s important use-case boundaries: it can organize awareness, but it should not become a substitute for a personal spending plan.
Stability, trust, and recovering from interruptions
Reliability matters more in a finance app than in many entertainment apps because a failed or delayed view can affect a real decision. I look for a calm experience: clear movement between money areas, predictable behavior when returning to the app, and enough context to avoid confusing a temporary loading state with a completed financial update. Upgrade - Boost Money’s value depends on that sense of confidence.
I would use it as a regular checkpoint, not as the only record of my finances. Keeping statements, notifications, or another secure record available is sensible, especially when an important payment or transfer is involved. If the app is interrupted while I am reviewing something, I would reopen it and verify the final state before acting. That recovery habit is more valuable than rushing through a transaction simply because the interface appears responsive.
The app’s relatively recent release and current version, 1.3.0, make update discipline especially relevant. I would keep automatic updates enabled where possible, then revisit the main screens after an update rather than assuming every control is exactly where it was. Early versions can improve quickly, but they can also change navigation or presentation as the developer responds to feedback. The 4.1 average indicates a generally positive reception with room for mixed experiences, so I would pay attention to how the app behaves in my own routine rather than relying only on the headline rating.
Recovery also includes recovering from my own mistakes. Before making a consequential financial decision, I would confirm the amount, destination, and timing in the final step. If I accidentally close the app or lose connectivity, I would check the account activity before trying again. Repeating an action without checking its status is a common way to create confusion, and no interface can remove that responsibility entirely.
Device limits and the right expectations for an early finance app
Upgrade - Boost Money requires Android 12 or newer, so compatibility is an immediate filter. Anyone using an older Android phone should not plan around it without first moving to a supported device. That requirement is not automatically a weakness; newer operating systems can provide a more consistent foundation. Still, it narrows the audience and may exclude users who keep older phones specifically to control household costs.
On a supported device, I would expect ordinary financial tasks to be more comfortable than demanding multimedia work. The app’s resource demands should generally be considered in relation to how often it is opened and how much information it has to present, not compared with games or video editors. I would avoid making precise claims about battery, storage, or data use because those can vary significantly with phone age, operating-system behavior, connection quality, and account activity.
A useful test is to try the app during the conditions in which I actually manage money: at home on a reliable connection, outside on mobile data, and after returning to it later in the day. If navigation remains understandable in those ordinary situations, that matters more to me than an impressive first launch. I would also avoid running financial tasks on a phone that is nearly full or badly out of date, because device-level problems can look like app problems.
People sharing devices or using a budget phone should think carefully about privacy and access habits. A finance app should be opened only on a device I control, with the phone’s own security protections enabled. The Everyone age rating describes the app’s content classification, not a recommendation that children manage financial accounts. Adults should remain responsible for account access, spending decisions, and any credit-related consequences.
Where it beats familiar alternatives, and where it does not
The usual alternative is to combine a bank app, a separate savings tool, and a credit-monitoring service. That arrangement can be powerful because each product may specialize in one job. It can also be tiring: different logins, different update schedules, and different ways of explaining balances or progress. Upgrade - Boost Money’s clearest advantage is the possibility of reducing that fragmentation.
Compared with a traditional bank app, this app’s identity is more focused on the connection between spending, saving, and credit-building. A bank app may remain the better choice for people who need a broad set of established banking operations in one place. Compared with a dedicated budgeting app, Upgrade - Boost Money may feel more relevant to someone who wants a direct relationship between daily spending and credit habits, while a specialized budget tool may offer deeper planning for complex households.
Compared with a credit-focused service, the app is more appealing if I want credit considerations alongside everyday money management rather than in isolation. However, anyone who needs advanced financial planning, detailed investment analysis, or a highly customized household budget may prefer specialized software. I would not choose this app simply because it combines several labels; I would choose it if that particular combination matches the way I make decisions.
A concrete example is a young worker managing irregular discretionary spending while trying to become more deliberate about credit. That person may benefit from checking spending and saving in the same place, then using the credit-building focus as a reminder to think long term. A family with multiple earners, complicated shared expenses, and extensive category rules may find a dedicated budgeting system easier to adapt. The right choice depends on whether simplicity or detailed control is the bigger problem.
Small workflows that make the app more useful
My first recommendation is to treat the app as a three-part review rather than a single dashboard glance. Start with spending: identify what has already happened. Move to saving: decide what amount can be protected without creating a shortfall. Finish with credit: consider whether the next action supports responsible, sustainable behavior. This order keeps immediate cash flow from being overshadowed by a longer-term goal.
My second recommendation is to use a “pause before purchase” rule for nonessential spending. I would check the current picture, mentally reserve upcoming fixed costs, and then decide whether the purchase belongs in today’s discretionary amount. This turns the app into a decision aid instead of a passive record. It is particularly useful when a purchase feels affordable in isolation but becomes uncomfortable after several similar purchases.
Third, I would review the app at a consistent weekly moment rather than only when money feels tight. A short review can reveal patterns that individual transactions hide, such as several small convenience purchases or a saving target that is too ambitious. If a target repeatedly forces me to move money back, I would lower it and make it sustainable. A realistic routine is more valuable than an impressive plan that collapses after a few days.
Finally, I would keep expectations precise. The app can help me organize behavior around spending, saving, and credit-building, but it cannot guarantee a particular financial outcome. Credit progress depends on responsible actions and broader circumstances, while saving depends on income, expenses, and consistency. The best result comes from using the app to make better decisions, not from treating it as an automatic solution.
Who should install it and who should look elsewhere
I think Upgrade - Boost Money is worth considering for someone who wants a free finance app with a combined focus and dislikes jumping among several services. It is especially suitable for users who prefer a simple recurring check-in, want spending and saving to remain visible together, and are interested in building more intentional credit habits. The modest install base does not make it unsuitable, but it does make me recommend a personal trial before moving every financial routine into it.
I would skip it if I need a mature, highly specialized system for investment management, detailed family accounting, or elaborate envelope budgeting. I would also skip it on an Android device below version 12, since the operating-system requirement makes compatibility a basic obstacle. Someone who already has a bank app and a trusted budgeting workflow may gain little unless the combined credit focus solves a specific problem.
The free price lowers the barrier to trying it, but free does not mean consequence-free. Financial decisions still require care, and I would never allow convenience to replace checking important details. The Everyone rating makes it broadly accessible from a content perspective, yet the subject matter remains adult and personal. I would install it only on a secure device and use it with a clear understanding of what I am trying to improve.
My performance verdict after fitting it into a money routine
My overall view is that Upgrade - Boost Money has a sensible reason to exist: it brings spending, saving, and credit-building into one finance experience instead of forcing users to manage each concern separately. I find that most valuable when I need a quick, calm check before making an everyday decision. The app’s performance should be judged by whether it keeps that routine understandable and dependable, not by whether it turns financial management into an instant process.
The main trade-off is breadth versus specialization. Combining several money goals can make the experience easier to approach, but it may not satisfy users who want deep controls in one narrow area. The Android 12 minimum also limits device choice, and the app’s relatively early version means I would remain attentive to updates and personal reliability. Those are practical considerations, not reasons to dismiss it.
For me, the best way to evaluate it is to begin with one contained workflow: use it for a weekly spending review, connect that review to a realistic saving decision, and then consider the credit-building goal separately. If that sequence reduces confusion and helps me act more consistently, the app is doing its job. If I still need several other tools for the decisions that matter most, then a bank app, dedicated budgeting product, or specialized credit service may be a better fit.
In short, this is a promising choice for people who want a single place to build better financial awareness without paying to experiment. I would recommend trying it with modest expectations, a secure supported device, and a backup habit for important records. The strongest reason to use it is not that it replaces every financial tool, but that it can make three connected money habits easier to review together.
4.1
51.00 Reviews
Pros
- Simple upgrade system makes progress easy to understand.
- Boosts can help speed up earnings during active sessions.
- Short gameplay loops work well for quick breaks.
- Bright visuals and clear menus are easy to navigate.
- Free access lets players try the core mechanics without paying.
Cons
- Progress may feel repetitive after extended play sessions.
- Some upgrades can take considerable time to unlock.
- Boost-focused mechanics may not appeal to every player.
- Ads may interrupt the experience or be used for extra rewards.
- The game may offer limited depth for experienced idle-game fans.


